Mortgages
Buy-to-let mortgages for landlords
Buy-to-let purchases, remortgages and how rental income is assessed.
- No obligation
- Takes 2 minutes
- Speak to a real adviser
- FCA regulated
- Whole-of-market
- 90+ lenders
- Personal adviser support
The short answer
Buy-to-let, explained in plain English.
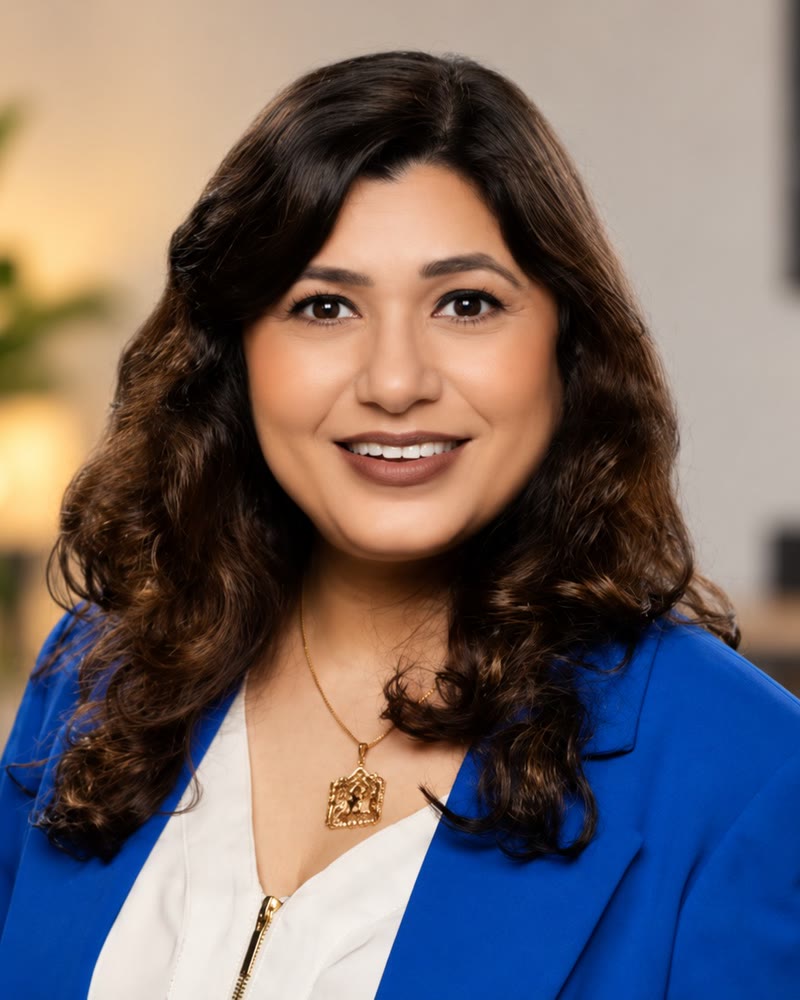
Written by Seema Babber, mortgage and protection adviser
Updated
Buy-to-let lenders mainly assess whether the expected rent covers the mortgage payment by a set margin, known as a rental stress test. Most require a deposit of at least 25%. Criteria differ for first-time landlords, limited company purchases and portfolio landlords, which is where advice helps.
Who this is for: New and experienced landlords buying or remortgaging a rental property, personally or through a limited company.
Your options
Your adviser compares these with you and explains the trade-offs before you decide.
Personal name
Buying in your own name, with rental income taxed as personal income.
Limited company
Buying through a company — different lenders, rates and tax treatment.
Portfolio landlords
Four or more mortgaged properties, assessed across the portfolio.
How it works
From first call to completion.
-
01
Check eligibility
We look at your deposit, income, experience and the expected rent.
-
02
Stress test the rent
We model how lenders will assess the rental cover.
-
03
Apply and value
We submit the application; the lender values the property and rent.
-
04
Complete
Legal work is completed and the mortgage is drawn down.
Before you start
Costs and risks to know about.
Costs to budget for
- Deposit — usually 25% or more
- Stamp Duty including the additional-property surcharge
- Lender fees, legal fees and valuation
- Our fee, if any — explained in writing first
Risks
Your property may be repossessed if you do not keep up repayments on your mortgage. Most buy-to-let mortgages are not regulated by the Financial Conduct Authority.
We explain the risks of any recommendation in writing before you proceed.
01How much deposit do I need?
Usually at least 25%, though some lenders need more depending on the property and rent.
02Can I be a first-time landlord?
Yes, some lenders accept first-time landlords, often with extra criteria such as owning your own home.
03Should I buy through a limited company?
It depends on your tax position. We explain the mortgage side and recommend speaking to an accountant.
Mortgage enquiry
Talk to an adviser about buy-to-let.
Takes about two minutes. An adviser will be in touch to talk through your options.
- 1What you need
- 2Property details
- 3Your details
- ✓Adviser follow-up
Why people enquire with us
- A named adviser and case handler look after your case
- We compare lenders across the market, not just one bank
- FCA regulated — firm reference 752191
- Phone, WhatsApp, video or at our Uxbridge office
Your details are kept secure and only used to handle your enquiry.