Buy-to-let borrowing
How much rent lenders need, and how much you could borrow against it.
You'll enter
- Expected monthly rent
- Property value
- Tax band
Mortgages
Buy-to-let purchases, remortgages and how rental income is assessed.
273 reviews
Trustpilot
4.9
from 213 reviews
Response time
Within 2 working hours
Chapter 01
Buy-to-let lenders mainly assess whether the expected rent covers the mortgage payment by a set margin, known as a rental stress test. Most require a deposit of at least 25%. Criteria differ for first-time landlords, limited company purchases and portfolio landlords, which is where advice helps.
Chapter 02
Buying in your own name, with rental income taxed as personal income.
Discuss this option: Personal nameBuying through a company — different lenders, rates and tax treatment.
Discuss this option: Limited companyFour or more mortgaged properties, assessed across the portfolio.
Discuss this option: Portfolio landlordsChapter 03
Step 1
We look at your deposit, income, experience and the expected rent.
Step 2
We model how lenders will assess the rental cover.
Step 3
We submit the application; the lender values the property and rent.
Step 4
Legal work is completed and the mortgage is drawn down.
Chapter 04
Chapter 05
How much rent lenders need, and how much you could borrow against it.
You'll enter
The monthly rent lenders are likely to need for the loan you want.
You'll enter
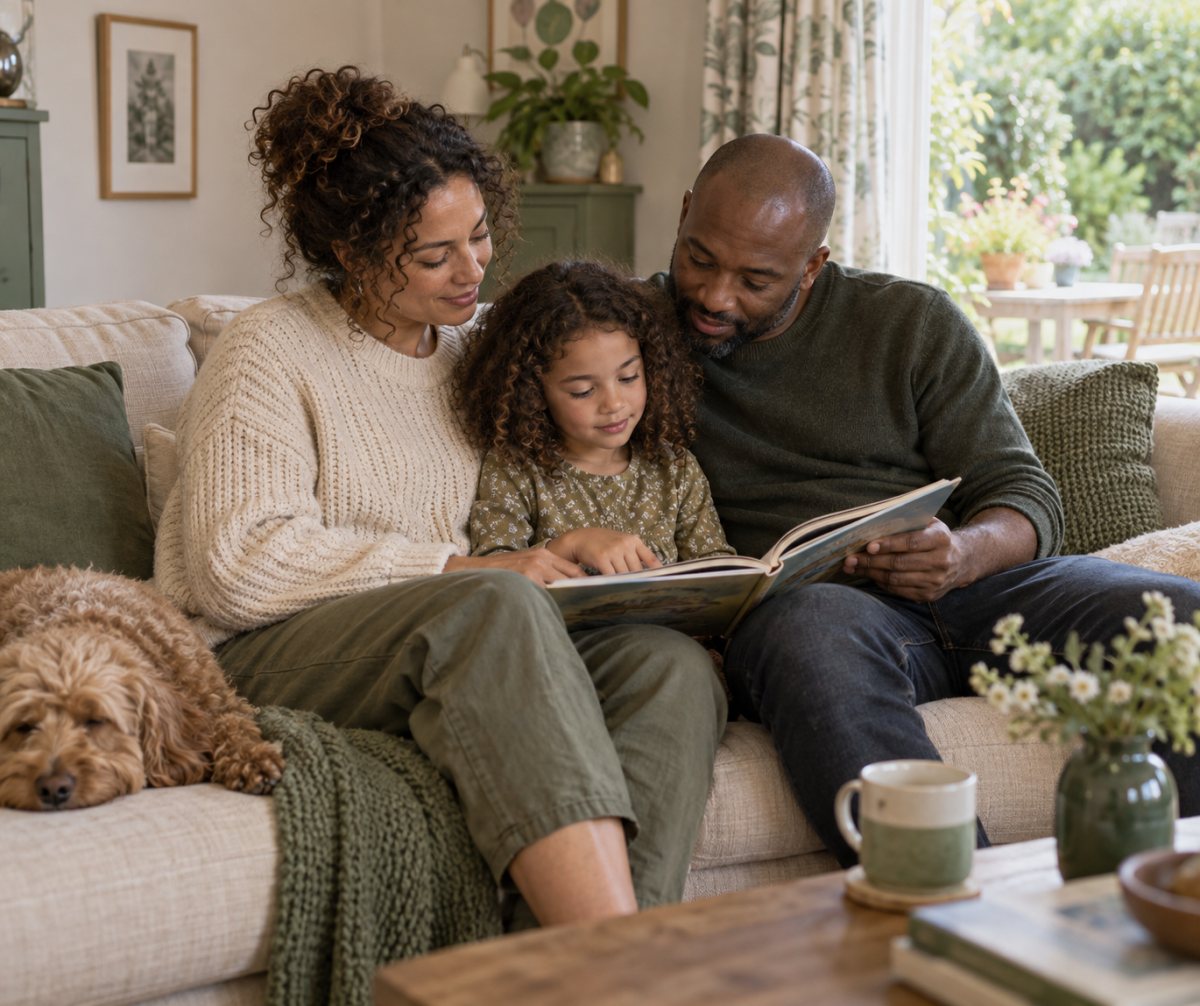
Life, income and critical illness cover, reviewed with your mortgage.
Explore protectionChapter 06
Reviews left for Zinga on Google and Trustpilot.
She was always quick to answer my questions, proactive in finding solutions, and dedicated to securing the right terms for my financial situation.
Many thanks to Arifa who quickly managed to get my mortgage application in principal then fully agreed. Great service thanks for your help.
Great experience easy to deal with
90+ lenders, including
Chapter 07
Didn't find your answer? An adviser can help.
Request a callbackUsually at least 25%, though some lenders need more depending on the property and rent.
Yes, some lenders accept first-time landlords, often with extra criteria such as owning your own home.
It depends on your tax position. We explain the mortgage side and recommend speaking to an accountant.
Chapter 08
Tell us a little about your plans and we'll call you back.